As featured in

Same lenders. A better deal through Juno.
Juno isn't a lender. We use the group buying power of our 299,000+ members to negotiate better deals with lenders, so you get perks you can't get by going direct.
Member rate discount and cash back are available with select lenders.

What is student loan refinancing?
Student loan refinancing is common, especially for people with private student loans, with an estimated 50,000 professionals doing so each month. It involves taking out a new student loan to pay off the existing debt you have, lowering your rate and overall cost.
Compare your options
There's no one size fits all for student loan refinance - that's why it's important to shop around and see your options. Most of our picks allow you to see rates in less than 10 minutes with a soft credit check, so you can get customized quotes without affecting your credit score.
For medical professionals
For medical professionals, Juno partners with two refinancing partners to offer additional benefits. When you become a Juno member, you'll be able to access cash back bonuses and interest rate discounts, for free.
Almost there!
Just enter your email to get a copy of this guide.
The power of numbers
- cash back earned by members
- $1.2M+
- members
- 299K+
- in loans
- $2B+
"I was with Sallie Mae and my interest rate was 10.75%, but I refinanced through [Juno] and not only got my rate down to almost 4%, but I also got $1000 cash. I got paid. To save money. [...] It's super easy and literally takes under 10 minutes. [...] Not everyone will save as much as me because I'm kind of an extreme case. I refinanced 170k at 10.75%V to 4.04%F, cutting my monthly payment from $2800 to $1250."

Josh C.
Juno member, Georgia Institute of Technology
Josh is a real Juno member. He shared this review on his own and was later compensated for permission to feature it here. Individual results may vary.
How it works
-
1
Fill out our quick form
Tell us a little about your loans and create your free Juno account. It takes about 2 minutes, and signing up doesn't commit you to anything.
-
2
Compare your rates
One form shows you rates from several lenders side by side, with your Juno perks included. It's a soft credit check, so it won't affect your credit score.
-
3
Complete the refinance
If you like your offer, apply with the lender through Juno to keep your perks. Your new lender pays off your old debt, and you begin making payments on your new loan.
Our approach
How we keep more money in your pocket
Lenders spend so much money on marketing. In comparison, 80%+ of our members find out about us from a friend.
We pitch lenders an alternative. Give our members better deals and avoid spending thousands of dollars per customer on marketing. It saves them time and money, and we end up getting our community better rates and cash back for free.
Can I refinance?
While we don't determine eligibility (our lending partners do), there are some basics that are usually needed:
- At least $5,000 in student loan debt
- No bankruptcies or defaults
- Attended a Title IV-accredited non-profit school
- Credit score above 650
- Employed with a steady income in USD
- U.S. Citizen or possess a 10-year (non-conditional) Permanent Resident Card
Note that while most lenders require a completed degree, one of our partners Earnest now has an option if you did not graduate. The last attending date needs to be longer than 6 years ago, and your credit needs to be above 700.
Customized rates
Looking for customized rates?
Get them in less than 5 minutes by just answering:
- Your name and email address
- Your citizenship status
- Degree, school and graduation date
- Credit score above 650
- Student loan balance
- Income
- Rent/mortgage payment
- Address
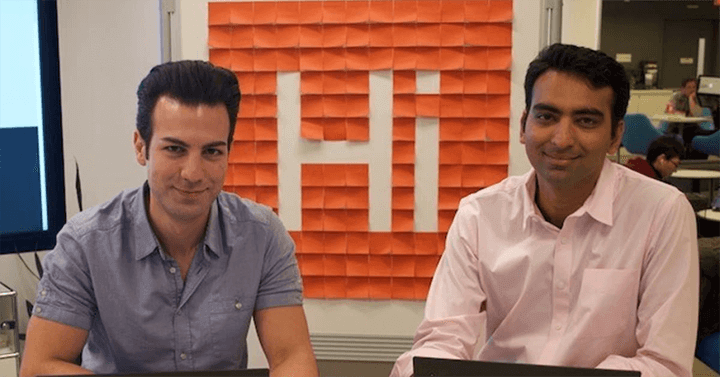
Our story
Started by two students with a tuition bill
Juno's founders, Nikhil Agarwal and Chris Abkarians, were admitted to Harvard Business School, and then the tuition bill came. Instead of taking expensive loans, they got 700 students from 10 schools together and negotiated lower rates for the entire group.
Juno exists to make that same benefit available to every student and graduate. Today, our community is 299,000+ members strong.
Why we're different
On your side of the table
Juno isn't a lender. We negotiate on behalf of our members and put their interests first when we evaluate and recommend lenders.
Lenders compete for you
Every year, we make lenders compete to offer the best deals to our community.
Free for members
Members never pay Juno. When you take out a loan through one of our partners, the lender pays us, not you.
Want to talk it through first?
Free consultations
Talk to a refinancing expert, free
Not sure refinancing is right for you? Juno's refi team offers free consultations for all borrowers, including medical and dental professionals managing six-figure loan balances. They can walk you through refinancing vs. forgiveness, IDR and PSLF, and how your offers compare.
Hosted by Joe from Juno
Reducing Student Loans 101 Webinar
Get smarter about how to reduce the burden of your student loan debt through refinancing. Juno's repayment expert discusses common questions, concerns and how the process works in this recorded webinar.
Looking to run some numbers?
We've got you covered with some helpful tools.

Common questions
Who is refinancing for?
Refinancing may be a good fit for borrowers who have higher-interest student loans and can qualify for a lower rate through a private lender.
This can include borrowers with private student loans whose current interest rates are higher than the rates available through refinancing. Lowering your rate could reduce the amount of interest you pay over the life of the loan, lower your monthly payment, or both, depending on the new loan term you select.
Borrowers with federal student loans may also be good candidates if they have higher interest rates and do not expect to benefit from federal programs such as Public Service Loan Forgiveness (PSLF) or income-driven repayment. Refinancing can be particularly worth exploring for borrowers with strong income and credit who plan to repay their loans in full and can qualify for meaningfully better terms.
You also don't have to refinance all of your student loans. You can choose which individual loans or balances to refinance while leaving others unchanged.
Important: Refinancing federal student loans with a private lender permanently converts those loans into private loans. You may lose federal benefits and protections, including income-driven repayment plans, Public Service Loan Forgiveness, certain deferment and forbearance options, and other federal borrower protections. Private refinancing terms, eligibility requirements, and borrower protections vary by lender. Student loans are also generally difficult to discharge in bankruptcy.
Before refinancing, carefully compare the potential savings with any benefits or protections you would be giving up. This information is for educational purposes only and is not financial advice. Consider your individual circumstances and, when appropriate, consult a qualified financial professional before making a decision.
What happens when you refinance?
Usually after people refinance a loan, we hear "why was that so easy?" The truth is that the process is fairly straightforward.
On a basic level, you're taking out a new loan to pay off your old loan.
Why does the term refinance still give me the willies?
The likely culprit: home mortgage refinance. Between closing costs, cash-out refinancing that involves moving other debt around, and potential loss of protections, this cousin of student loan refinance gives all refinance a bad rep.
In contrast, student loan refi through Juno doesn't have any fees involved, and is basically a straight 1:1 refinance - you can only get a new loan covering the cost of your existing student debt, so you can't borrow more than what you already owe. Student loan refi typically doesn't involve collateral, unlike home mortgage refi where your house can be foreclosed on if you don't pay your mortgage bills. As always, please consult a financial advisor for additional context.
Remember, refinancing private student loan debt typically doesn't result in the loss of protections; refinancing federal student loan debt can result in the loss of certain protections (income-driven repayment, forbearance options, etc). You can always pick and choose what you'd like to refinance without affecting all your loans.
Is now a good time to refinance private student loans?
Rates change over time, so it is always worth checking what rates are available to you. Plus, don't forget that you have the option to refinance multiple times. Some of our members refinance their loans once a year if they can get a better rate.
What about Parent PLUS loans?
Yes! All of our partners allow you to refinance Parent PLUS loans. Sometimes people want to change the name of the loan holder. Depending on the partner, it may be possible to refinance the loan into your child's name. Individual results may vary.
- With Earnest, you can only refinance loans already in your name as the primary borrower. If your parent is the primary borrower, the original lender may be able to transfer the loan from the parent to you, and then Earnest can refinance in your name.
- It is possible to refinance a Parent PLUS loan into your child's name with SoFi, but your child must apply. Please contact their Customer Support to learn more.
- Laurel Road does allow you to refinance a Parent PLUS directly into your name.
Got more questions? Drop us a line at hello@joinjuno.com.